DETACHED HOME SALES IMPROVE IN SEPTEMBER
SEPTEMBER 2026 Calgary Market Update DETACHED HOME SALES IMPROVE IN SEPTEMBER Calgary, Alberta, Oct. 1, 2026 – September sales totalled 1,650 units, similar to August
City of Calgary, July 2, 2025
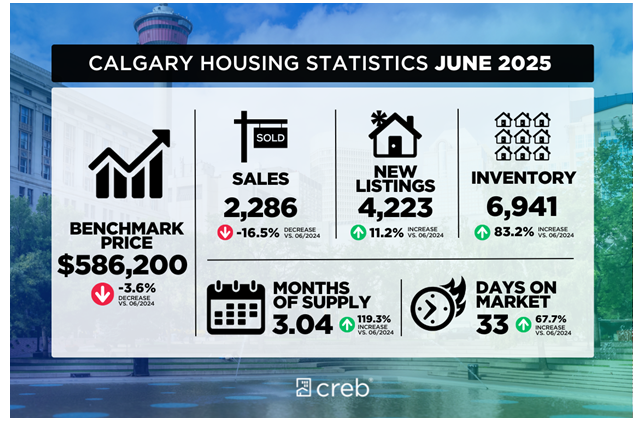
Inventory levels in June continued to rise, both over last month’s and last year’s levels. By the end of the month, inventory reached 6,941 units, returning to levels reported in 2021, or prior to the surge in population growth. While sales have remained consistent with long-term trends despite a decline from recent months, higher levels of new listings compared to sales have contributed to the inventory gain.
All property types have reported gains in inventory, but both row and apartment style homes reported inventory levels over 30 per cent higher than long-term trends, while supply for detached and semi-detached units are only slightly higher than typical levels.
“Supply has improved across rental, resale and new home markets, allowing for more choice for those considering their housing options,” said Ann-Marie Lurie, Chief Economist at CREB®. “The additional choice combined with no further declines in lending rates, persistent uncertainty and concerns of price adjustments is keeping many potential purchasers on the sidelines. This is weighing on home prices, especially for apartment and row style homes.”
The unadjusted benchmark price was $586,200 in June, lower than last month and over three per cent lower than last year. Much of the citywide decline was driven by apartment and row style homes, which are over three per cent lower.
Much of the citywide decline was driven by apartment and row style homes, which are over three per cent lower than last year. Meanwhile, detached prices have remained relatively stable and semi-detached homes are still slightly higher than last year.
The steeper price declines for apartment and row style homes are reflective of those segments shifting toward a market that favours the buyer with nearly four months of supply. Meanwhile conditions are relatively balanced for detached and semi-detached homes. Overall conditions in Calgary have changed, but not enough to erase the significant growth in prices that have occurred over the past four years.
Sales in June were 1,194 units, six per cent lower than both last year and last month’s activity. Sales activity did vary depending on location and price range, with declines in resale sales mostly for higher priced homes that likely face more competition from new homes. On a location basis, the steepest declines in sales occurred in the City Centre and the North East at over 20 per cent, while year-over-year gains were reported in the West, and South East districts.
While sales did vary, inventories and new listings improved across most price ranges and districts in the city. However, it is only the North East district that is experiencing conditions that favour the buyer, causing prices to decline by four per cent compared to last June. As of June, the unadjusted benchmark price in Calgary was $764,300, less than one per cent lower than both last month and last year’s price.
New listings continue to rise relative to the number of sales in the market, as the sales-to-new listings ratio in June dropped to 50 percent. This contributed to further inventory gains with 1,167 units available at the end of the month. While sales are still higher than long-term trends, the recent gains in inventory levels have caused the months of supply to push above three months. Within the city, conditions range with nearly six months of supply in the North East and two and a half months of supply in the North West.
Higher supply levels relative to demand are weighing on prices which, at a June
benchmark price of $450,300, are down over last month and three per cent lower
than last year’s levels. However, as the level of oversupply does range across
the districts, so too do the price movements. The City Centre has seen the most
stability in prices this month and is only one per cent below last year’s peak.
Meanwhile, the North East is reporting year-over-year price declines of nearly
six per cent.
Sales activity continued to slow this month, contributing to the year-to-date decline of nearly 12 per cent. At the same time new listings have generally been rising compared to last year, supporting inventory gains and a shift to balanced conditions. As of June, the months of supply was 2.6 months, a significant improvement over the tight conditions reported last year.
Additional supply choice has slowed the pace of price growth for semi-detached homes. As of June, the benchmark price in the city was $696,400, similar to last month, and over one per cent higher than last June. Price movements did range by district, as homes in the City Centre are over three per cent higher than last year and at record high levels, while prices in the North, North East, and East districts are all over two per cent lower than last year and three per cent lower than last year’s peak price.
APARTMENT CONDOMINIUM
June new listings and sales both eased over last month’s and last year’s levels. However, with 1,024 new listings and 532 sales, inventories continued to rise and the months of supply pushed up to nearly four months. Slower international migration numbers are weighing on housing demand just as supply levels are rising, which is having a larger impact on apartment style homes.
The rising supply choice, both in new and resale markets, has caused resale prices to trend down again this month, leaving June’s benchmark price of $333,500 over three per cent lower than last year’s levels. While prices have eased across all districts in the city, the largest year-over-year declines are occurring in the North East, North and South East districts.

SEPTEMBER 2026 Calgary Market Update DETACHED HOME SALES IMPROVE IN SEPTEMBER Calgary, Alberta, Oct. 1, 2026 – September sales totalled 1,650 units, similar to August

AUGUST 2026 Calgary Market Update SALES AND NEW LISTINGS SLOW IN AUGUST Calgary, Alberta, September 1, 2026 – Consistent with trends throughout most of 2026,

JUNE 2026 Calgary Market Update City of Calgary, July 2, 2026 HIGH-DENSITYSUPPLY IMPACTS APARTMENT CONDOMINIUM PRICES Calgary, Alberta, July 2, 2026 – sales in
City of Calgary, August 1, 2023 – Rising rates had little impact on sales this month as the 2,647 sales represented a year-over-year gain of 18 per cent, reflecting the strongest July levels reported on record. The record-setting pace has been driven mainly by significant gains in the relatively affordable apartment condominium sector. Despite recent gains, year-to-date sales have declined by 19 per cent over last year.
In line with seasonal expectations, sales and new listings trended down compared to last month. However, this had minimal impact on inventory levels, which remained near the July record low set in 2006. With a sales-to-new-listings ratio of 82 per cent and a month of supply of 1.3 months, conditions continue to favor the seller.
The unadjusted benchmark price was $586,200 in June, lower than last month and over three per cent lower than last year. Much of the citywide decline was driven by apartment and row style homes, which are over three per cent lower than last year. Meanwhile, detached prices have remained relatively stable and semi-detached homes are still slightly higher than last year.
The steeper price declines for apartment and row style homes are reflective of those segments shifting toward a market that favours the buyer with nearly four months of supply. Meanwhile conditions are relatively balanced for detached and semi-detached homes. Overall conditions in Calgary have changed, but not enough to erase the significant growth in prices that have occurred over the past four years.
With 1,197 sales and 1,587 new listings in July, inventory levels trended up over last month. However, with 1,720 units available, inventory levels are at the lowest ever reported for July. Inventory levels have declined across all properties priced below $1,000,000. Shifts in sales and inventory have caused the months of supply to trend up over the one month reported over the past several months. However, conditions remain relatively tight, and prices continued to rise this month. In July, the unadjusted
benchmark price rose to $690,500, a monthly gain of nearly one per cent and
over seven per cent higher than last July. Both year-over-year and monthly
price growth was strongest in the city’s most affordable North East and East
Districts.
While row sales, new listings and inventory levels have all trended up compared to levels seen at the start of the year, like other property types, levels are much lower than last year. With one month of supply available, conditions continue to favor the seller. The tight market conditions also placed further upward pressure on prices.
In March, the benchmark price rose to $378,100, reflecting a year-over-year gain of nearly eight per cent and representing a new monthly record high. Price growth was strongest in the city’s North East and South districts, with the lowest year-over-year gains occurring in the West district.
With only 248 new listings in July and 211 sales, the sales-to-new-listings ratio once again pushed above 85 percent. The pullback in new listings relative to sales ensured that inventory levels remained low, and the months of supply remained just over one month. With no shift in the sellers ‘market conditions, the unadjusted benchmark price
continued to trend up in July, reaching $616,800. Monthly gains were strongest
in the North East and East districts both rose by over two percent compared to
June. The only district that experienced stability in monthly prices was the
City Centre
APARTMENT CONDOMINIUM
July sales continued to rise over last year’s levels, leaving year-to-date sales 16 per cent higher than levels reported last year. This is the only property type that has reported a year-to-date gain in sales activity. This has been possible thanks to recent gains in new listings. However, conditions remain tight for apartment condominiums with a sales-new-listings ratio of 84 percent and a months of supply of1.4 months. The strong demand relative to supply for this property type has driven further price gains this month. As of July, the unadjusted benchmark price reached $305,900, nearly one per cent higher than last month and over 12 per cent higher than last July. While prices are higher than last year in every district, the city center has yet to see the same level of pressure on prices and has reported the lowest year-over-year growth at nearly nine percent.

SEPTEMBER 2026 Calgary Market Update DETACHED HOME SALES IMPROVE IN SEPTEMBER Calgary, Alberta, Oct. 1, 2026 – September sales totalled 1,650 units, similar to August

AUGUST 2026 Calgary Market Update SALES AND NEW LISTINGS SLOW IN AUGUST Calgary, Alberta, September 1, 2026 – Consistent with trends throughout most of 2026,

JUNE 2026 Calgary Market Update City of Calgary, July 2, 2026 HIGH-DENSITYSUPPLY IMPACTS APARTMENT CONDOMINIUM PRICES Calgary, Alberta, July 2, 2026 – sales in