DETACHED HOME SALES IMPROVE IN SEPTEMBER
SEPTEMBER 2026 Calgary Market Update DETACHED HOME SALES IMPROVE IN SEPTEMBER Calgary, Alberta, Oct. 1, 2026 – September sales totalled 1,650 units, similar to August
City of Calgary, January 2nd, 2025
2024 MARKS ANOTHER STRONG YEAR FOR SALES AND PRICE GROWTH
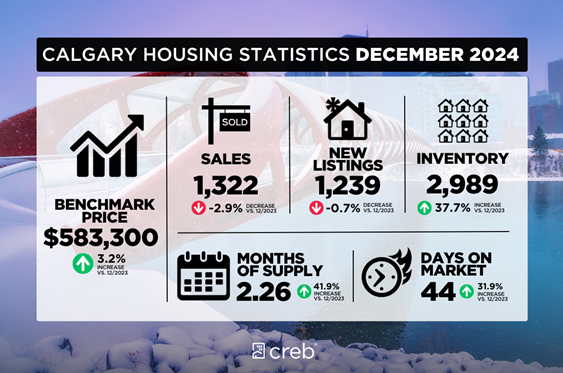
The year ended with 1,322 sales in December, a three per cent decline over last year, but nearly 20 per cent higher than long-term trends. Overall sales in 2024 were just shy of last year’s levels, as gains for higher-priced homes offset pullbacks in the lower price ranges caused by supply challenges.
“Population gains over the past several years have supported sales activity that has outperformed long-term trends. In 2024, sales would likely have been higher if there was more supply choice, especially in the lower price ranges,” said Ann-Marie Lurie, Chief Economist at CREB®. “That being said, we did start to see shifts occurring in the market in the second half of the year as supply levels started to improve for higher priced homes.”
As of December, there were 2,989 units available in inventory, still below long-term trends for the month but a significant improvement over the lower levels reported last December and levels reported early this year. Improved rental choice and significant gains in new home activity helped boost new listings in the resale market, driving higher inventories in the year’s second half.
While conditions vary depending on price range and property type, more housing options have helped to take some of the pressure off home prices, which stabilized in the second half of the year following steep gains in the spring. Overall, on an annual basis, total residential benchmark prices improved by over seven per cent.
As we move into 2025, supply will continue to be a dominant theme. However, how they impact prices will ultimately depend on the type of supply being added and how demand holds up in the face of a changing economic climate. On January 21, CREB® will release its forecast report, highlighting the expectations and risks facing the market in the coming year.
Easing lending rates have likely supported some recent year-over-year gains in detached home sales over the past three months. Improving sales were driven by gains for homes over $600,000, which also reported improvements in new listings. Inventory levels did improve within city limits for detached homes; however, conditions varied across districts. The City Centre, Northeast and North District all reported relatively balanced conditions over the last quarter of the year, while all other districts continued to struggle with seller market conditions.
The relatively tight market conditions throughout the year caused prices to rise by nearly eleven per cent in 2024, a faster pace than what was reported in 2023. Much of that growth occurred during spring when supply levels were exceptionally low. Prices grew across all districts, with the strongest growth occurring in the most affordable districts of the Northeast and East
In 2024, there were 4,647 row home sales, a gain of over two per cent compared to last year and the second-highest total on record. The growth in sales was possible thanks to the 18 per cent gain in new listings, most of which occurred for homes priced above $400,000—the gains in new listings relative to sales supported inventory growth in 2024.
By the year’s end, supply improvements helped take the pressure off home prices. However, the annual benchmark price rose by 14 per cent as conditions favoured the seller throughout the year. Prices rose across all districts in the city, with the gains ranging from a low of 12 per cent in the city centre to over 20 per cent in the most affordable districts in the Northeast and East.
Limited supply choice for lower-priced detached homes drove many purchasers toward the semi-detached sector. In 2024, there were 2,355 sales, with an annual gain of five per cent. Thanks to gains in new listings relative to sales, inventory levels started to improve, supporting a shift toward more balanced conditions by the fourth quarter. However, much of this shift occurred in the higher-priced City Centre district, where the months of supply averaged three months in the last quarter.
The annual average benchmark price increased by nearly 11 per cent to $669,042 in 2024. Like detached homes, exceptionally tight conditions throughout the spring caused the pace of price growth to rise over the seven per cent annual gain reported in 2023. Prices improved across all districts, ranging from an annual gain of under 10 per cent in the City Centre and West to gains exceeding 15 per cent in the North East and East districts.
APARTMENT CONDOMINIUM
Easing sales in the second half of the year offset earlier gains, causing apartment sales to slow by four per cent compared to last year. However, last year was a record high for sales, and the 7,568 transactions this year reflect the second-highest year on record. At the same time, new listings have been on the rise, supporting inventory gains and a shift toward more balanced conditions by the end of the year.
As more supply became available, we did see some price adjustments in the last quarter of the year. However, the quarterly decline did not offset the strong gains that occurred earlier in the year, and the annual benchmark price rose by 15 per cent. Price growth ranged from a low of 11 per cent in the city centre to over twenty per cent in the Northeast, East and South districts.

SEPTEMBER 2026 Calgary Market Update DETACHED HOME SALES IMPROVE IN SEPTEMBER Calgary, Alberta, Oct. 1, 2026 – September sales totalled 1,650 units, similar to August

AUGUST 2026 Calgary Market Update SALES AND NEW LISTINGS SLOW IN AUGUST Calgary, Alberta, September 1, 2026 – Consistent with trends throughout most of 2026,

JUNE 2026 Calgary Market Update City of Calgary, July 2, 2026 HIGH-DENSITYSUPPLY IMPACTS APARTMENT CONDOMINIUM PRICES Calgary, Alberta, July 2, 2026 – sales in
City of Calgary, August 1, 2023 – Rising rates had little impact on sales this month as the 2,647 sales represented a year-over-year gain of 18 per cent, reflecting the strongest July levels reported on record. The record-setting pace has been driven mainly by significant gains in the relatively affordable apartment condominium sector. Despite recent gains, year-to-date sales have declined by 19 per cent over last year.
In line with seasonal expectations, sales and new listings trended down compared to last month. However, this had minimal impact on inventory levels, which remained near the July record low set in 2006. With a sales-to-new-listings ratio of 82 per cent and a month of supply of 1.3 months, conditions continue to favor the seller.
“Continued migration to the province, along with our relative affordability, has supported the stronger demand for housing despite higher lending rates,” said CREB® Chief Economist Ann-Marie Lurie. “At the same time, we continue to struggle with supply in the resale, new home and rental markets resulting in further upward pressure on home prices.”
In July, the unadjusted total residential benchmark price reached $567,700, marking the seventh consecutive monthly gain. Prices are now over four per cent higher than the previous peak in May of 2022.
With 1,197 sales and 1,587 new listings in July, inventory levels trended up over last month. However, with 1,720 units available, inventory levels are at the lowest ever reported for July. Inventory levels have declined across all properties priced below $1,000,000. Shifts in sales and inventory have caused the months of supply to trend up over the one month reported over the past several months. However, conditions remain relatively tight, and prices continued to rise this month. In July, the unadjusted
benchmark price rose to $690,500, a monthly gain of nearly one per cent and
over seven per cent higher than last July. Both year-over-year and monthly
price growth was strongest in the city’s most affordable North East and East
Districts.
While row sales, new listings and inventory levels have all trended up compared to levels seen at the start of the year, like other property types, levels are much lower than last year. With one month of supply available, conditions continue to favor the seller. The tight market conditions also placed further upward pressure on prices.
In March, the benchmark price rose to $378,100, reflecting a year-over-year gain of nearly eight per cent and representing a new monthly record high. Price growth was strongest in the city’s North East and South districts, with the lowest year-over-year gains occurring in the West district.
With only 248 new listings in July and 211 sales, the sales-to-new-listings ratio once again pushed above 85 percent. The pullback in new listings relative to sales ensured that inventory levels remained low, and the months of supply remained just over one month. With no shift in the sellers ‘market conditions, the unadjusted benchmark price
continued to trend up in July, reaching $616,800. Monthly gains were strongest
in the North East and East districts both rose by over two percent compared to
June. The only district that experienced stability in monthly prices was the
City Centre
APARTMENT CONDOMINIUM
July sales continued to rise over last year’s levels, leaving year-to-date sales 16 per cent higher than levels reported last year. This is the only property type that has reported a year-to-date gain in sales activity. This has been possible thanks to recent gains in new listings. However, conditions remain tight for apartment condominiums with a sales-new-listings ratio of 84 percent and a months of supply of1.4 months. The strong demand relative to supply for this property type has driven further price gains this month. As of July, the unadjusted benchmark price reached $305,900, nearly one per cent higher than last month and over 12 per cent higher than last July. While prices are higher than last year in every district, the city center has yet to see the same level of pressure on prices and has reported the lowest year-over-year growth at nearly nine percent.

SEPTEMBER 2026 Calgary Market Update DETACHED HOME SALES IMPROVE IN SEPTEMBER Calgary, Alberta, Oct. 1, 2026 – September sales totalled 1,650 units, similar to August

AUGUST 2026 Calgary Market Update SALES AND NEW LISTINGS SLOW IN AUGUST Calgary, Alberta, September 1, 2026 – Consistent with trends throughout most of 2026,

JUNE 2026 Calgary Market Update City of Calgary, July 2, 2026 HIGH-DENSITYSUPPLY IMPACTS APARTMENT CONDOMINIUM PRICES Calgary, Alberta, July 2, 2026 – sales in